Unit 06 · Chapter 2 · 10 min read

Consumer protection, errors, and complaints

Design a clear path from customer report to a supported resolution.

A customer calls a transfer wrong. The first task is to understand the report and route it under the right rules. The customer should not need to know the name of a regulation to reach the correct process.

Determine the product and account scope

Consumer error-resolution rights depend on the relevant law, product, account, transaction, and facts. Regulation E covers specified electronic fund transfers and related requirements; other products and processes can have different rules. A card-network dispute process does not replace every statutory duty.

Build intake fields that establish the relevant scope without asking the customer to classify the law. Record the account type, transaction reference, alleged error, report time, and supporting facts. Route ambiguity to a qualified owner. Avoid a universal reimbursement or denial rule based only on an internal fraud label.
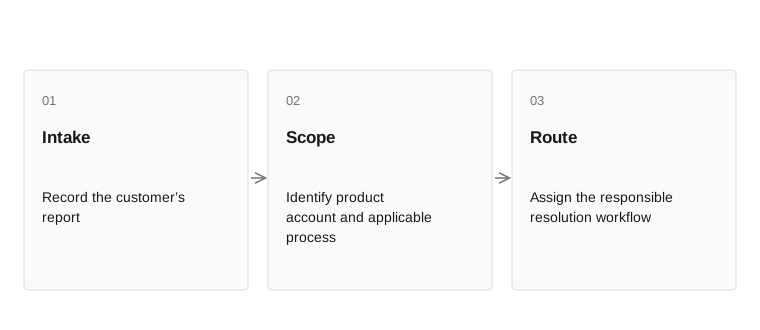
Determine the product and account scope — the flow
Determine the product and account scope Determine the product and account scope — the flow Follow the sequence. Assign the responsible resolution workflow. Intake Record the customer’s report Scope Identify product account and applicable process Route Assign the responsible resolution workflow
  1. IntakeRecord the customer’s report
  2. ScopeIdentify product account and applicable process
  3. RouteAssign the responsible resolution workflow
Follow the sequence. Assign the responsible resolution workflow. Chapter sources · Open image
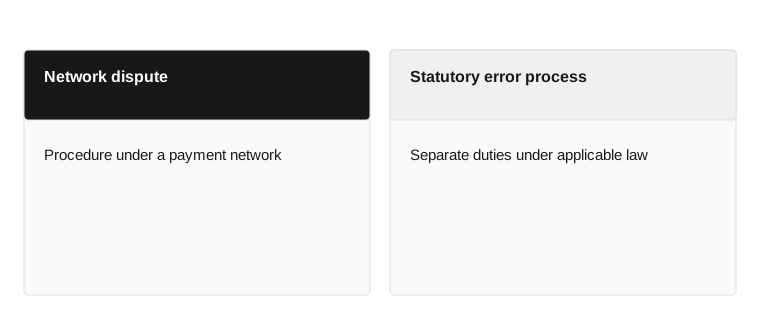
Determine the product and account scope — the distinction
Determine the product and account scope Determine the product and account scope — the distinction These concepts answer different questions. Read each definition in the context of the section. Network dispute Procedure under a payment network Statutory error process Separate duties under applicable law
Network dispute
  • Procedure under a payment network
Statutory error process
  • Separate duties under applicable law
These concepts answer different questions. Read each definition in the context of the section. Chapter sources · Open image
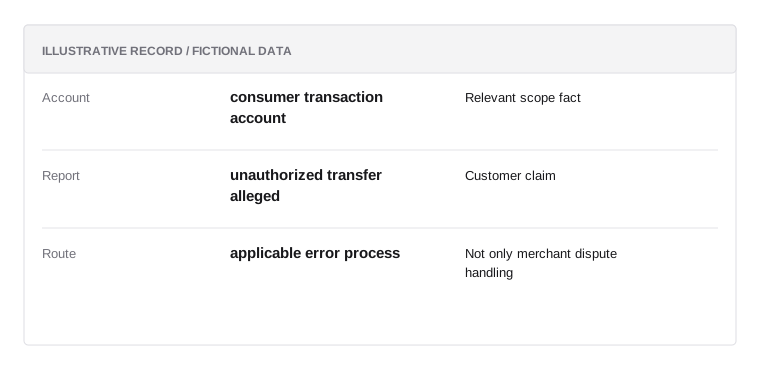
Error intake
Determine the product and account scope Error intake Fictional teaching record. Not only merchant dispute handling. Error intake Illustrative data; not a real customer record or a prescribed policy. Account consumer transaction account Relevant scope fact Report unauthorized transfer alleged Customer claim Route applicable error process Not only merchant dispute handling The customer need not name the regulation
Fictional educational excerpt / Not for execution

Error intake

Illustrative data; not a real customer record or a prescribed policy.

  1. Accountconsumer transaction account

    Relevant scope fact

  2. Reportunauthorized transfer alleged

    Customer claim

  3. Routeapplicable error process

    Not only merchant dispute handling

The customer need not name the regulation

Fictional teaching record. Not only merchant dispute handling. Chapter sources · Open image
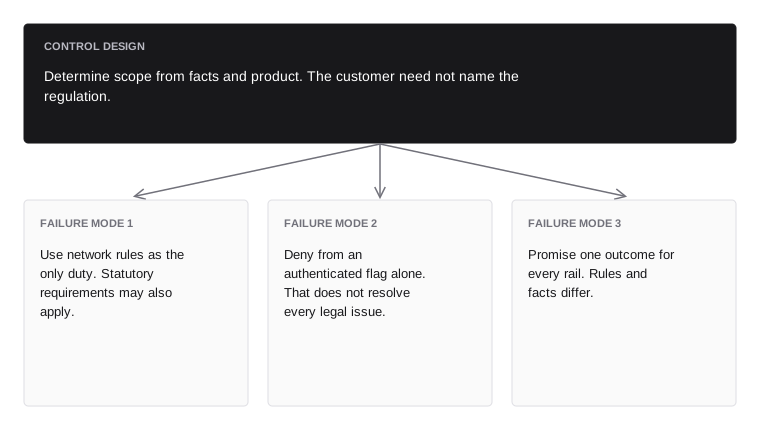
Determine the product and account scope — control and failure modes
Determine the product and account scope Determine the product and account scope — control and failure modes The customer need not name the regulation. The branches show why alternative designs fail. Control design Determine scope from facts and product. The customer need not name the regulation. Failure mode 1 Use network rules as the only duty. Statutory requirements may also apply. avoid Failure mode 2 Deny from an authenticated flag alone. That does not resolve every legal issue. avoid Failure mode 3 Promise one outcome for every rail. Rules and facts differ. avoid
Control design

Determine scope from facts and product. The customer need not name the regulation.

Failure mode 1avoid
Use network rules as the only duty. Statutory requirements may also apply.
Failure mode 2avoid
Deny from an authenticated flag alone. That does not resolve every legal issue.
Failure mode 3avoid
Promise one outcome for every rail. Rules and facts differ.
The customer need not name the regulation. The branches show why alternative designs fail. Chapter sources · Open image

Capture the report without friction

A customer report may arrive by phone, message, branch, or another supported channel. Preserve the original time and content. Internal reassignment should not erase the report date or force the customer to restart the process.

Use a shared reference and a clear acknowledgment. Collect the information necessary for investigation while following the applicable requirements for any written confirmation or documentation. Do not create extra intake barriers merely because the case tool prefers a complete form. The workflow should distinguish missing helpful evidence from a report that has already triggered a duty.

Customer language rarely arrives in the institution’s preferred taxonomy. A person may say “the money vanished” when the issue involves a duplicate transfer, an unexpected amount, a pending hold, or an unfamiliar payment. Intake should preserve the customer’s statement and collect the facts needed for classification. It should not require the person to know the legal label before the institution can recognize a potentially covered issue.

Make the handoff durable. A chat transcript, telephone note, or support ticket may contain information that starts an important process. Define how that information reaches the responsible team and how the original receipt time is preserved. Routing delays should not silently reset the institution’s understanding of when it learned about the report.
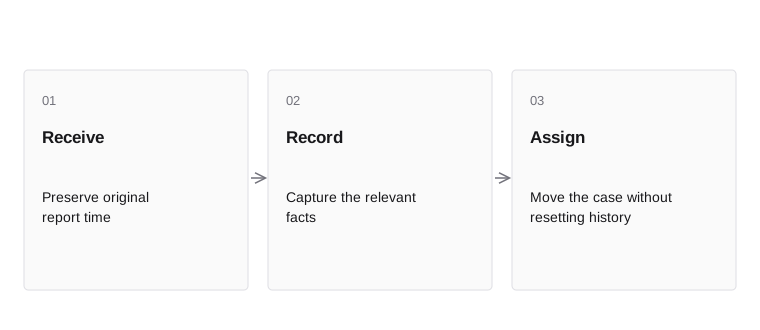
Capture the report without friction — the flow
Capture the report without friction Capture the report without friction — the flow Follow the sequence. Move the case without resetting history. Receive Preserve original report time Record Capture the relevant facts Assign Move the case without resetting history
  1. ReceivePreserve original report time
  2. RecordCapture the relevant facts
  3. AssignMove the case without resetting history
Follow the sequence. Move the case without resetting history. Chapter sources · Open image
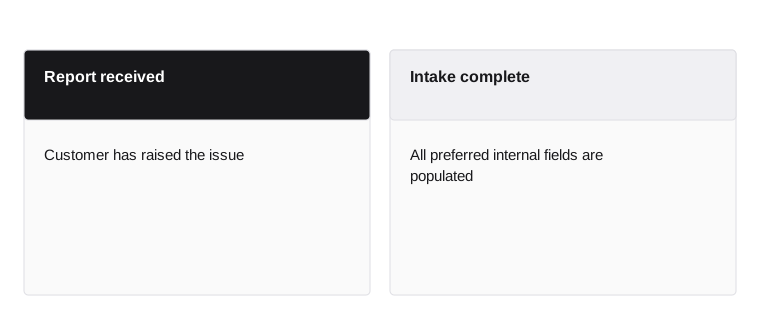
Capture the report without friction — the distinction
Capture the report without friction Capture the report without friction — the distinction These concepts answer different questions. Read each definition in the context of the section. Report received Customer has raised the issue Intake complete All preferred internal fields are populated
Report received
  • Customer has raised the issue
Intake complete
  • All preferred internal fields are populated
These concepts answer different questions. Read each definition in the context of the section. Chapter sources · Open image
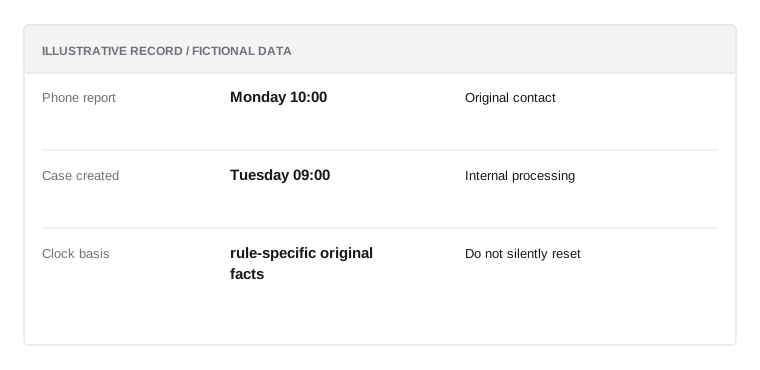
Channel handoff
Capture the report without friction Channel handoff Fictional teaching record. Do not silently reset. Channel handoff Illustrative data; not a real customer record or a prescribed policy. Phone report Monday 10:00 Original contact Case created Tuesday 09:00 Internal processing Clock basis rule-specific original facts Do not silently reset Internal tooling must not rewrite the customer event
Fictional educational excerpt / Not for execution

Channel handoff

Illustrative data; not a real customer record or a prescribed policy.

  1. Phone reportMonday 10:00

    Original contact

  2. Case createdTuesday 09:00

    Internal processing

  3. Clock basisrule-specific original facts

    Do not silently reset

Internal tooling must not rewrite the customer event

Fictional teaching record. Do not silently reset. Chapter sources · Open image
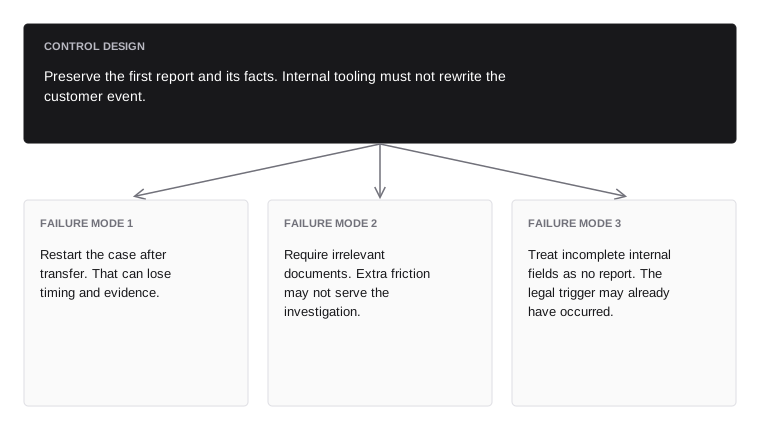
Capture the report without friction — control and failure modes
Capture the report without friction Capture the report without friction — control and failure modes Internal tooling must not rewrite the customer event. The branches show why alternative designs fail. Control design Preserve the first report and its facts. Internal tooling must not rewrite the customer event. Failure mode 1 Restart the case after transfer. That can lose timing and evidence. avoid Failure mode 2 Require irrelevant documents. Extra friction may not serve the investigation. avoid Failure mode 3 Treat incomplete internal fields as no report. The legal trigger may already have occurred. avoid
Control design

Preserve the first report and its facts. Internal tooling must not rewrite the customer event.

Failure mode 1avoid
Restart the case after transfer. That can lose timing and evidence.
Failure mode 2avoid
Require irrelevant documents. Extra friction may not serve the investigation.
Failure mode 3avoid
Treat incomplete internal fields as no report. The legal trigger may already have occurred.
Internal tooling must not rewrite the customer event. The branches show why alternative designs fail. Chapter sources · Open image

Investigate the actual alleged error

The investigation should address the reported issue: unauthorized use, wrong amount, duplicate transfer, missing credit, or another covered error. Authentication, device, and merchant records are evidence with limits. A correct password does not answer every question about authority or deception.

Build an evidence plan specific to the allegation. For a duplicate transfer, compare logical operation identifiers and ledger entries. For a missing credit, trace settlement and posting. Keep the conclusion tied to the facts and applicable standards. Avoid using a generic system worked response when the relevant records were never examined.
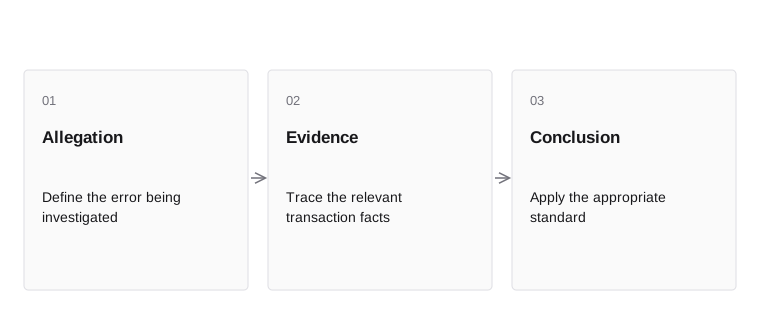
Investigate the actual alleged error — the flow
Investigate the actual alleged error Investigate the actual alleged error — the flow Follow the sequence. Apply the appropriate standard. Allegation Define the error being investigated Evidence Trace the relevant transaction facts Conclusion Apply the appropriate standard
  1. AllegationDefine the error being investigated
  2. EvidenceTrace the relevant transaction facts
  3. ConclusionApply the appropriate standard
Follow the sequence. Apply the appropriate standard. Chapter sources · Open image
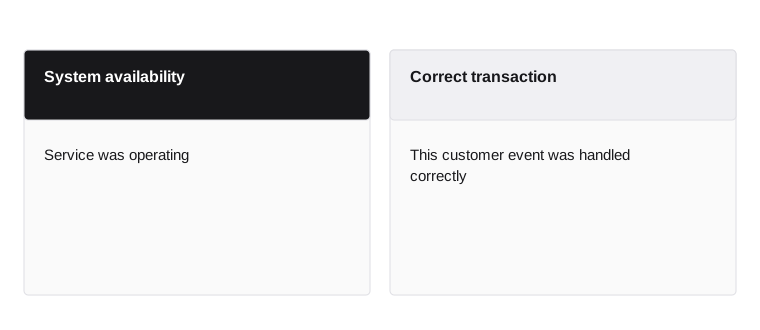
Investigate the actual alleged error — the distinction
Investigate the actual alleged error Investigate the actual alleged error — the distinction These concepts answer different questions. Read each definition in the context of the section. System availability Service was operating Correct transaction This customer event was handled correctly
System availability
  • Service was operating
Correct transaction
  • This customer event was handled correctly
These concepts answer different questions. Read each definition in the context of the section. Chapter sources · Open image
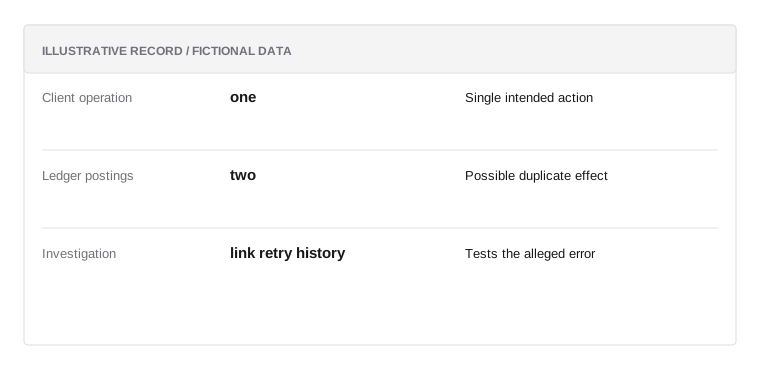
Duplicate-transfer evidence
Investigate the actual alleged error Duplicate-transfer evidence Fictional teaching record. Tests the alleged error. Duplicate-transfer evidence Illustrative data; not a real customer record or a prescribed policy. Client operation one Single intended action Ledger postings two Possible duplicate effect Investigation link retry history Tests the alleged error Generic uptime evidence does not resolve it
Fictional educational excerpt / Not for execution

Duplicate-transfer evidence

Illustrative data; not a real customer record or a prescribed policy.

  1. Client operationone

    Single intended action

  2. Ledger postingstwo

    Possible duplicate effect

  3. Investigationlink retry history

    Tests the alleged error

Generic uptime evidence does not resolve it
Fictional teaching record. Tests the alleged error. Chapter sources · Open image
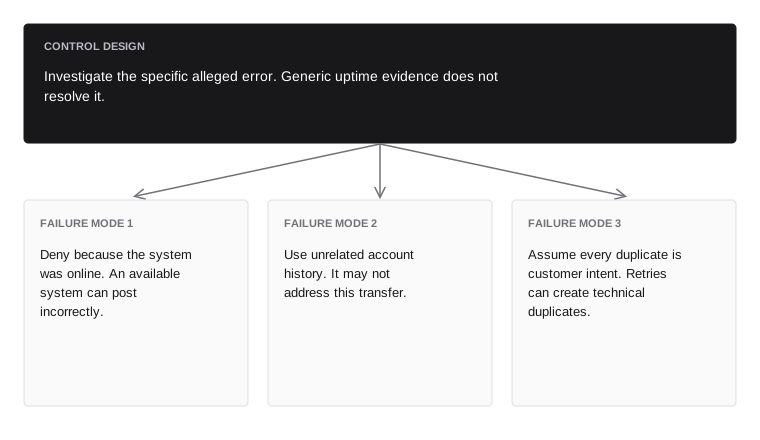
Investigate the actual alleged error — control and failure modes
Investigate the actual alleged error Investigate the actual alleged error — control and failure modes Generic uptime evidence does not resolve it. The branches show why alternative designs fail. Control design Investigate the specific alleged error. Generic uptime evidence does not resolve it. Failure mode 1 Deny because the system was online. An available system can post incorrectly. avoid Failure mode 2 Use unrelated account history. It may not address this transfer. avoid Failure mode 3 Assume every duplicate is customer intent. Retries can create technical duplicates. avoid
Control design

Investigate the specific alleged error. Generic uptime evidence does not resolve it.

Failure mode 1avoid
Deny because the system was online. An available system can post incorrectly.
Failure mode 2avoid
Use unrelated account history. It may not address this transfer.
Failure mode 3avoid
Assume every duplicate is customer intent. Retries can create technical duplicates.
Generic uptime evidence does not resolve it. The branches show why alternative designs fail. Chapter sources · Open image

Model credits notices and final outcomes

Some error-resolution processes can require provisional credit under defined conditions. Provisional and final credit are different states. The applicable deadlines, exceptions, notices, and reversal conditions must come from the relevant rule and facts.

Use a ledger-backed workflow that records the type of credit and links it to the case. Customer messaging should explain the actual status without promising finality prematurely. If a later change is permitted, apply the required process and preserve the evidence. An operational shortcut that edits a balance without a linked case creates confusion and weakens review.

Financial adjustments and notices must remain consistent with the case outcome. If a provisional credit is used under the applicable process, the ledger should identify its nature and link it to the investigation. A later change requires the approved transition, customer communication, and any applicable timing or access treatment. Store actual amounts and dates rather than reconstructing them from ticket comments. Support can then explain what the customer can use now and what remains subject to the investigation.
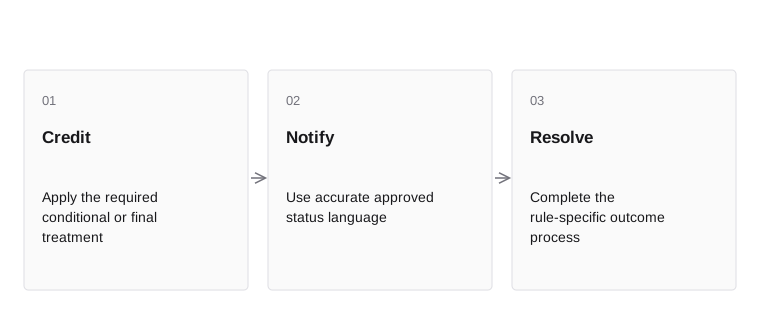
Model credits notices and final outcomes — the flow
Model credits notices and final outcomes Model credits notices and final outcomes — the flow Follow the sequence. Complete the rule-specific outcome process. Credit Apply the required conditional or final treatment Notify Use accurate approved status language Resolve Complete the rule-specific outcome process
  1. CreditApply the required conditional or final treatment
  2. NotifyUse accurate approved status language
  3. ResolveComplete the rule-specific outcome process
Follow the sequence. Complete the rule-specific outcome process. Chapter sources · Open image
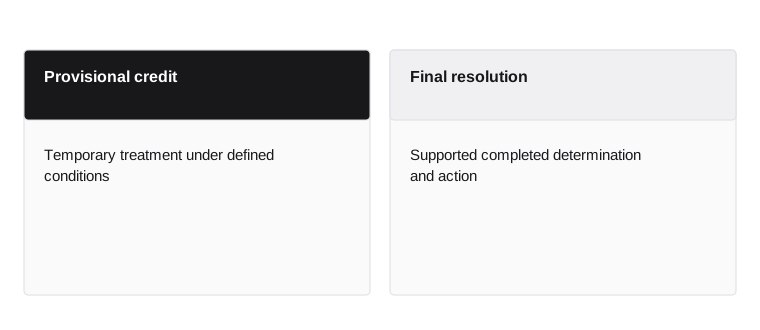
Model credits notices and final outcomes — the distinction
Model credits notices and final outcomes Model credits notices and final outcomes — the distinction These concepts answer different questions. Read each definition in the context of the section. Provisional credit Temporary treatment under defined conditions Final resolution Supported completed determination and action
Provisional credit
  • Temporary treatment under defined conditions
Final resolution
  • Supported completed determination and action
These concepts answer different questions. Read each definition in the context of the section. Chapter sources · Open image
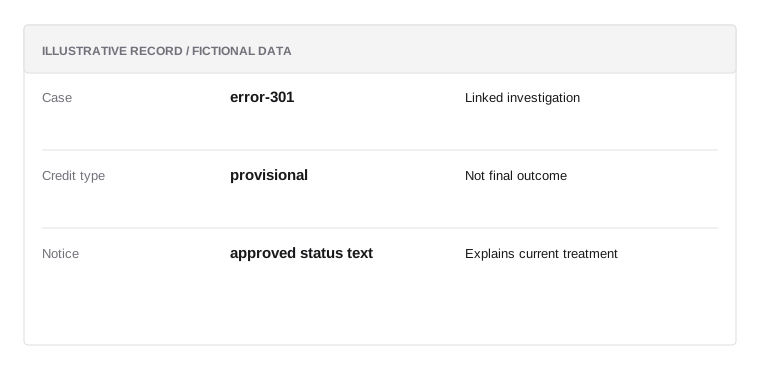
Credit record
Model credits notices and final outcomes Credit record Fictional teaching record. Explains current treatment. Credit record Illustrative data; not a real customer record or a prescribed policy. Case error-301 Linked investigation Credit type provisional Not final outcome Notice approved status text Explains current treatment Customer understanding and ledger treatment depend on it
Fictional educational excerpt / Not for execution

Credit record

Illustrative data; not a real customer record or a prescribed policy.

  1. Caseerror-301

    Linked investigation

  2. Credit typeprovisional

    Not final outcome

  3. Noticeapproved status text

    Explains current treatment

Customer understanding and ledger treatment depend on it

Fictional teaching record. Explains current treatment. Chapter sources · Open image
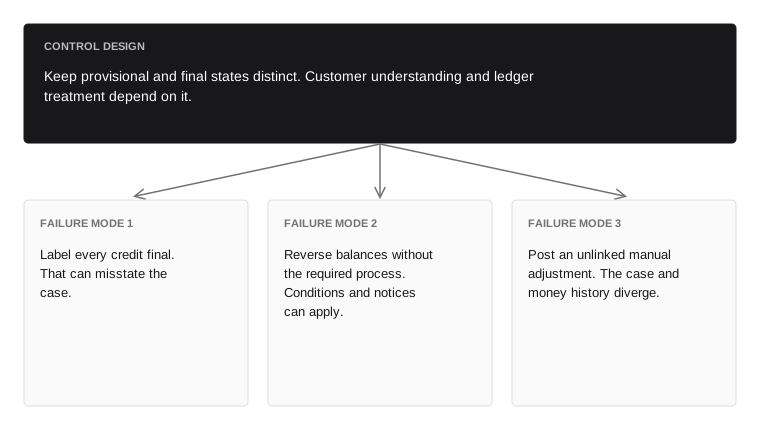
Model credits notices and final outcomes — control and failure modes
Model credits notices and final outcomes Model credits notices and final outcomes — control and failure modes Customer understanding and ledger treatment depend on it. The branches show why alternative designs fail. Control design Keep provisional and final states distinct. Customer understanding and ledger treatment depend on it. Failure mode 1 Label every credit final. That can misstate the case. avoid Failure mode 2 Reverse balances without the required process. Conditions and notices can apply. avoid Failure mode 3 Post an unlinked manual adjustment. The case and money history diverge. avoid
Control design

Keep provisional and final states distinct. Customer understanding and ledger treatment depend on it.

Failure mode 1avoid
Label every credit final. That can misstate the case.
Failure mode 2avoid
Reverse balances without the required process. Conditions and notices can apply.
Failure mode 3avoid
Post an unlinked manual adjustment. The case and money history diverge.
Customer understanding and ledger treatment depend on it. The branches show why alternative designs fail. Chapter sources · Open image

Use complaints as product evidence

Complaints can reveal confusing descriptions, broken cancellation, inaccessible recovery, delayed funds, or unfair treatment. Categorize the issue and root cause without treating every complaint as proof of wrongdoing.

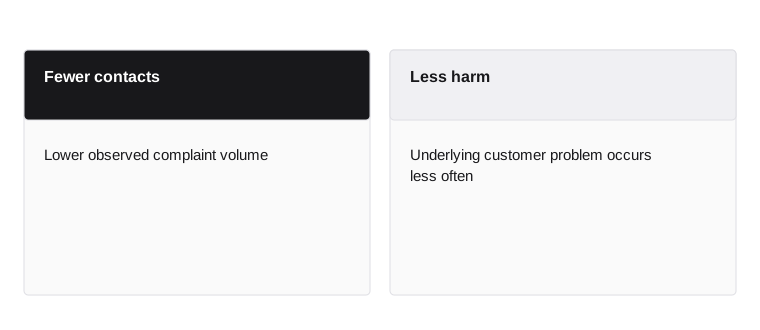
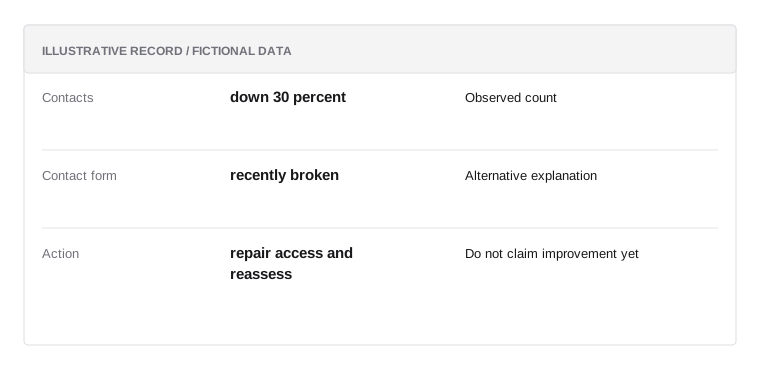
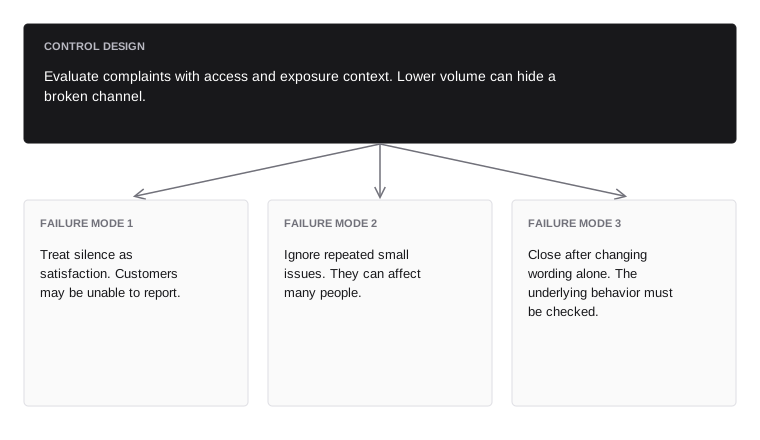
Analyze rates with relevant denominators and compare themes across channels. A drop in complaints may reflect a harder contact path rather than better service. Feed confirmed patterns into product and control changes. Track whether the change reduces the underlying harm, not only the number of messages reaching the queue.
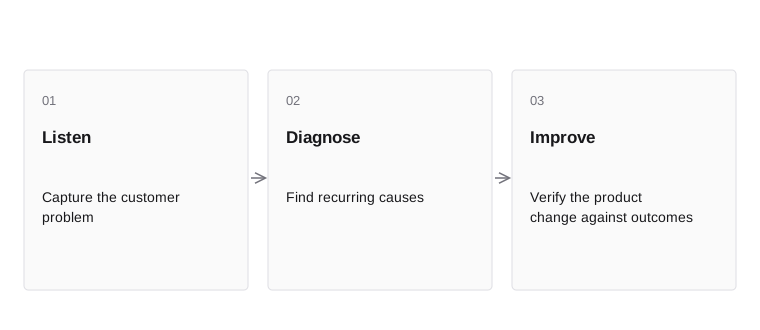
Use complaints as product evidence — the flow
Use complaints as product evidence Use complaints as product evidence — the flow Follow the sequence. Verify the product change against outcomes. Listen Capture the customer problem Diagnose Find recurring causes Improve Verify the product change against outcomes
  1. ListenCapture the customer problem
  2. DiagnoseFind recurring causes
  3. ImproveVerify the product change against outcomes
Follow the sequence. Verify the product change against outcomes. Chapter sources · Open image
Use complaints as product evidence — the distinction
Use complaints as product evidence Use complaints as product evidence — the distinction These concepts answer different questions. Read each definition in the context of the section. Fewer contacts Lower observed complaint volume Less harm Underlying customer problem occurs less often
Fewer contacts
  • Lower observed complaint volume
Less harm
  • Underlying customer problem occurs less often
These concepts answer different questions. Read each definition in the context of the section. Chapter sources · Open image
Complaint trend
Use complaints as product evidence Complaint trend Fictional teaching record. Do not claim improvement yet. Complaint trend Illustrative data; not a real customer record or a prescribed policy. Contacts down 30 percent Observed count Contact form recently broken Alternative explanation Action repair access and reassess Do not claim improvement yet Lower volume can hide a broken channel
Fictional educational excerpt / Not for execution

Complaint trend

Illustrative data; not a real customer record or a prescribed policy.

  1. Contactsdown 30 percent

    Observed count

  2. Contact formrecently broken

    Alternative explanation

  3. Actionrepair access and reassess

    Do not claim improvement yet

Lower volume can hide a broken channel
Fictional teaching record. Do not claim improvement yet. Chapter sources · Open image
Use complaints as product evidence — control and failure modes
Use complaints as product evidence Use complaints as product evidence — control and failure modes Lower volume can hide a broken channel. The branches show why alternative designs fail. Control design Evaluate complaints with access and exposure context. Lower volume can hide a broken channel. Failure mode 1 Treat silence as satisfaction. Customers may be unable to report. avoid Failure mode 2 Ignore repeated small issues. They can affect many people. avoid Failure mode 3 Close after changing wording alone. The underlying behavior must be checked. avoid
Control design

Evaluate complaints with access and exposure context. Lower volume can hide a broken channel.

Failure mode 1avoid
Treat silence as satisfaction. Customers may be unable to report.
Failure mode 2avoid
Ignore repeated small issues. They can affect many people.
Failure mode 3avoid
Close after changing wording alone. The underlying behavior must be checked.
Lower volume can hide a broken channel. The branches show why alternative designs fail. Chapter sources · Open image

Chapter connections

This chapter builds on Compliance architecture and policy as code. Continue with Fair lending, explainability, and adverse action to follow the next part of the system. Use the glossary for terminology and risk mathematics for formulas and worked calculations.

Sources

Reviewed 2026-09-17
  1. Regulation E, 12 CFR 1005.11: error resolution
  2. Regulation E, 12 CFR 1005.6: unauthorized-transfer liability
  3. Stripe: how disputes work (provider example)